
Money & Economics
- Thread starter bigredfish
- Start date
You are using an out of date browser. It may not display this or other websites correctly.
You should upgrade or use an alternative browser.
You should upgrade or use an alternative browser.


Great article
 www.zerohedge.com
… For years, the United States has responded to financial crises with some combination of lower interest rates, enormous fiscal deficits and extraordinary amounts of liquidity. Whenever something breaks badly enough, policymakers rush in to stabilize the system. By now, I’m hoping people are starting to realize that when this happens, the benefits and costs of these “rescues” aren’t distributed evenly.
In fact, they disproportionately brutalize the middle and lower class, the very same group of citizens that politicians are almost always claiming to help. And such rescues are almost always supported by both political parties. (Read: The Devil Neither Political Party Will Name)
In these situations, financial assets can respond almost immediately to easier money and abundant liquidity. Stocks rise. Bonds rise. Real estate rises. Private-company valuations rise. People who already own substantial assets watch their net worth recover and, eventually, soar.
The person living paycheck to paycheck experiences this very differently. He doesn’t own enough stocks for another bull market to change his life. Instead, he notices that his rent costs more. His groceries cost more. Insurance costs more. Restaurants cost more. A starter home that was already expensive becomes completely unattainable.
….Back in the day, inflation would slow (but never reverse) and economists would announce that the problem was getting better. But the middle and lower class was still stuck with higher rent, groceries and home prices. Nowadays, inflation hasn’t even slowed. Prices are still skyrocketing higher. And the middle and lower class is getting torn to shreds by higher prices.
And that is the political environment that produces Zohran Mamdani…demonizing billionaires, proposing extremely regressive taxes, advocating for social revolution and just throwing around ideas of a state planned economy like he’s talking about the weather to a passerby in the park.
Which brings us to the great irony: the anger underlying his politics can be legitimate even if his proposed solutions make little sense on paper and even less sense in reality.
As I’ve said innumerable times on this blog, a voter doesn’t need to understand the Federal Reserve’s balance sheet to recognize that something feels profoundly wrong when working full time no longer seems sufficient to achieve the basic milestones previous generations considered normal.
And when that voter hears that the stock market has hit another record high, he doesn’t feel richer. He feels cheated…and pissed off…and envious.
More here
The Fed Created Zohran Mamdani
The Fed Created Zohran Mamdani<!-- --> | ZeroHedge
ZeroHedge - On a long enough timeline, the survival rate for everyone drops to zero
www.zerohedge.com
… For years, the United States has responded to financial crises with some combination of lower interest rates, enormous fiscal deficits and extraordinary amounts of liquidity. Whenever something breaks badly enough, policymakers rush in to stabilize the system. By now, I’m hoping people are starting to realize that when this happens, the benefits and costs of these “rescues” aren’t distributed evenly.
In fact, they disproportionately brutalize the middle and lower class, the very same group of citizens that politicians are almost always claiming to help. And such rescues are almost always supported by both political parties. (Read: The Devil Neither Political Party Will Name)
In these situations, financial assets can respond almost immediately to easier money and abundant liquidity. Stocks rise. Bonds rise. Real estate rises. Private-company valuations rise. People who already own substantial assets watch their net worth recover and, eventually, soar.
The person living paycheck to paycheck experiences this very differently. He doesn’t own enough stocks for another bull market to change his life. Instead, he notices that his rent costs more. His groceries cost more. Insurance costs more. Restaurants cost more. A starter home that was already expensive becomes completely unattainable.
….Back in the day, inflation would slow (but never reverse) and economists would announce that the problem was getting better. But the middle and lower class was still stuck with higher rent, groceries and home prices. Nowadays, inflation hasn’t even slowed. Prices are still skyrocketing higher. And the middle and lower class is getting torn to shreds by higher prices.
And that is the political environment that produces Zohran Mamdani…demonizing billionaires, proposing extremely regressive taxes, advocating for social revolution and just throwing around ideas of a state planned economy like he’s talking about the weather to a passerby in the park.
Which brings us to the great irony: the anger underlying his politics can be legitimate even if his proposed solutions make little sense on paper and even less sense in reality.
As I’ve said innumerable times on this blog, a voter doesn’t need to understand the Federal Reserve’s balance sheet to recognize that something feels profoundly wrong when working full time no longer seems sufficient to achieve the basic milestones previous generations considered normal.
And when that voter hears that the stock market has hit another record high, he doesn’t feel richer. He feels cheated…and pissed off…and envious.
More here

Chokolinho
Known around here

You Have To Like Bonds Here...Right?
You Have To Like Bonds Here...Right?<!-- --> | ZeroHedge
ZeroHedge - On a long enough timeline, the survival rate for everyone drops to zero
www.zerohedge.com
You have to start to like bonds here a little, right? Here’s how I’m thinking about it.
With equities, over long periods, investors generally expect annual returns of roughly 7% to 8%, albeit with plenty of volatility and drawdowns along the way. Here’s Vanguard’s 10 year annualized forecast for various sectors:
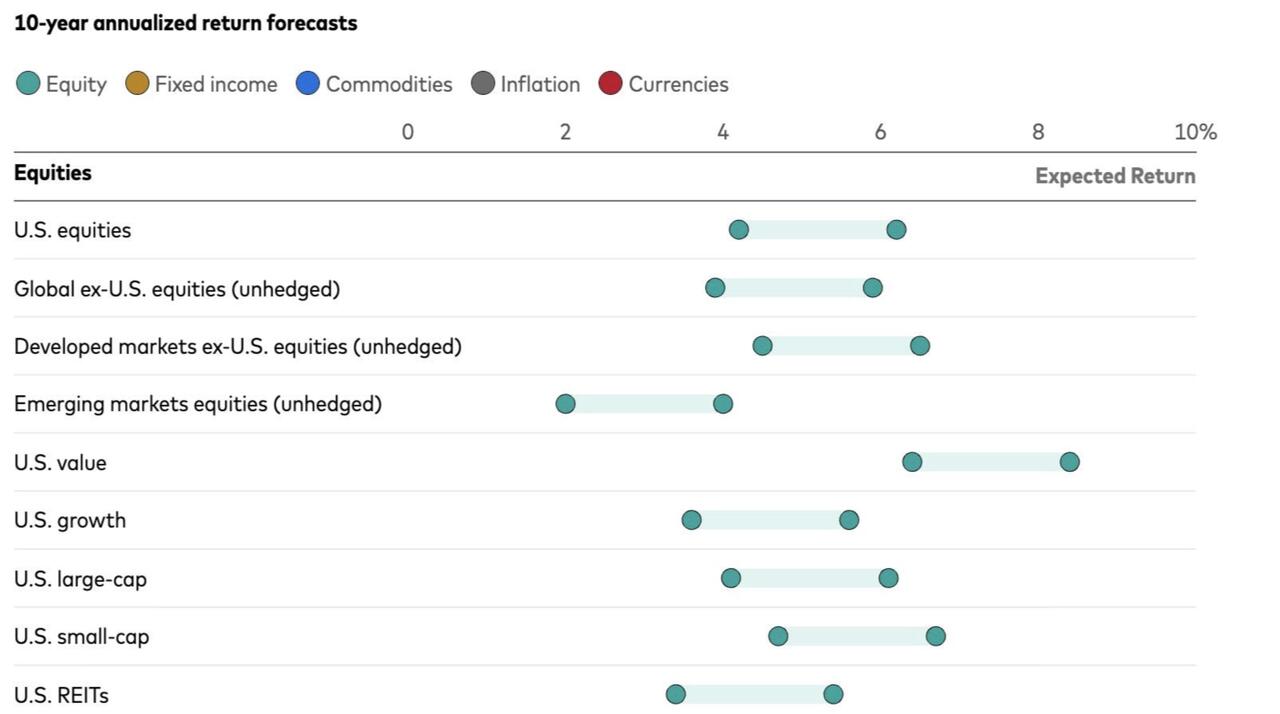
More importantly, these are roughly the returns the participants in our global Ponzi scheme need to generate just to keep whatever charade they are running going for another year…whether it is a pension fund, managing an endowment, overseeing an insurance portfolio, or simply trying to meet some actuarial assumption that was made decades ago.
So if “risk-free” Treasuries are now paying more than 5%, the gap between the two (the “risk free” trade and the requirement from equities) starts narrowing and getting noticeable.
Today, with the 10-year Treasury yield at roughly 5.25%, this is how I approach bonds...(READ THIS FULL ARTICLE HERE).

More articles by the same guy. I follow him
 quoththeraven.substack.com
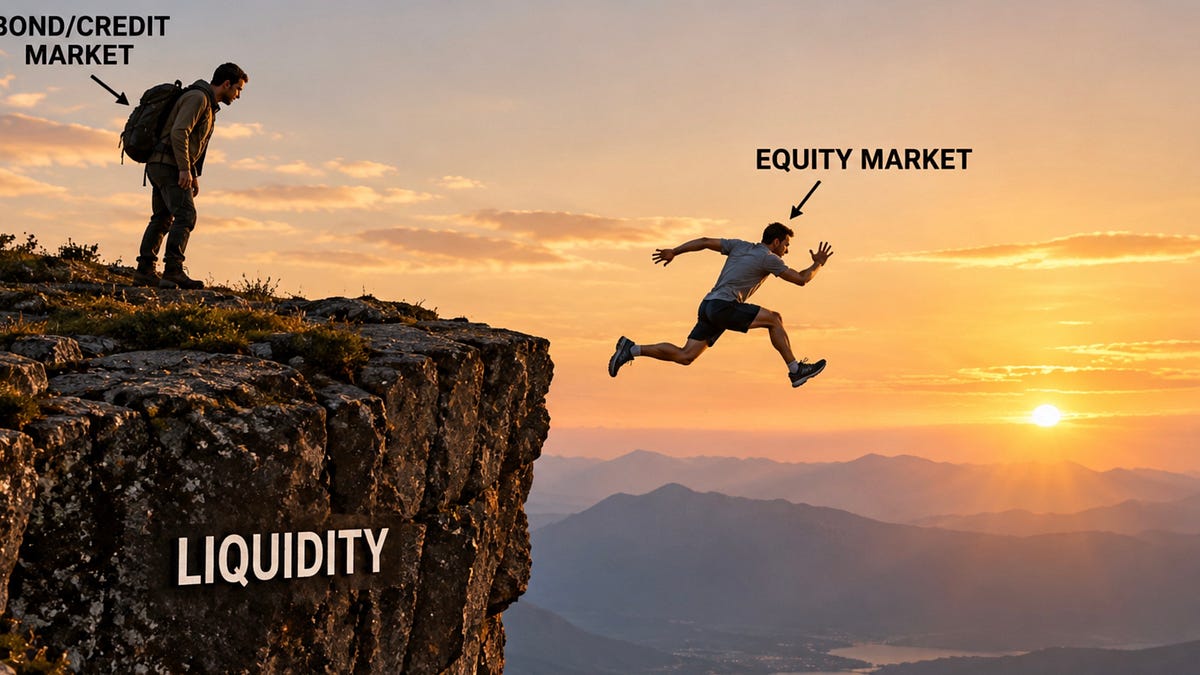
............ In other words, the global cost of capital is repricing higher at exactly the same moment that the internals of the U.S. equity market are deteriorating, and as…in my opinion only…the wheels of the AI trade are starting to fall off in a big way.
The S&P 500 is increasingly behaving like a mansion whose foundation is starting to crack while everybody stands on the roof admiring the view. The capitalization-weighted index remains elevated because a handful of gigantic companies, particularly those associated with the AI trade, carry enough weight to offset weakness almost everywhere else.
But equal-weight stocks are falling. Banks are falling. Midcaps and small caps have been hit harder. Fewer stocks are holding their moving averages. The median stock is nowhere near its high. And those are precisely the areas, along with unprofitable small cap shitcos that need constant capital to survive, where you would expect higher financing costs to begin showing themselves first.
===========================================
 quoththeraven.substack.com
Put all of this together and the picture starts becoming difficult to dismiss as a collection of unrelated curiosities.
..........The question under this AI bubble is what price investors were willing to pay for the future before that future actually arrives, and whether the economics eventually produced by the technology could justify the enormous amount of capital committed to it along the way.
For the first time during this cycle, we’re beginning to get enough information to actually run those numbers and the credit markets and bond markets are puking them back up at record speed. The cost of capital is rising while the financial statements behind some of the most celebrated companies in the world are finally being laid bare, forcing investors to confront the possibility that enormous technological importance and enormous economic profitability may not necessarily arrive on the same timetable.
Underneath all of the breathless talk about trillion dollar addressable markets and civilization changing productivity, the uncomfortable possibility is that there may not be nearly as much “there” there economically as current valuations have already priced in…at least for this credit cycle.
Investors can now see the financial statements, the credit spreads, the bond yields, the deterioration in market breadth and the extraordinary capital requirements necessary to keep the AI machine running for themselves. The information isn’t hidden anymore. What remains unclear is who will be the first person willing to look at all of it together and simply proclaim that the AI emperor has no clothes…and what happens when everybody else realizes they were just sitting around waiting for someone else to say it first.
==============================================
 quoththeraven.substack.com
............The reason is simple. Higher rates restore consequences. When investors can earn meaningful returns in Treasury securities and other relatively safe assets, they no longer need to finance every revolutionary dog walking blockchain SaaS platform that comes along. Junk bonds have to offer genuinely attractive yields. Private credit has to compete against liquid alternatives. Venture investments have to offer enough potential return to compensate for years of illiquidity and enormous failure rates.
Suddenly, the hurdle rate exists again.
Companies burning cash discover that capital has a price. Companies dependent on refinancing discover that lenders have alternatives. Private equity firms discover that an acquisition financed with cheap debt looks considerably less brilliant when that debt has to be refinanced at twice the rate. Commercial real estate owners discover that capitalization rates matter. Governments discover that deficits carry interest expense. Investors discover that earnings expected fifteen years from now are worth substantially less when the discount rate is no longer zero.
Fraud becomes harder…because fraud loves liquidity. It needs it for sustenance. Liquidity buys time, and a questionable business can survive as long as somebody keeps funding it. Once capital becomes scarce, the runway shortens and the questions become considerably less philosophical. Where is the cash? Who owes whom? What is the collateral actually worth? Can you refinance this? Why does EBITDA never turn into free cash flow? Why are you issuing stock every quarter? Why does every supposedly temporary adjustment show up again next year?
Why, exactly, does this multi-billion dollar company make no fucking money?
........... Higher rates will not make markets perfectly rational either. Markets have been doing stupid things for hundreds of years and will presumably continue doing stupid things long after all of us are dead. But the environment in which stupidity operates matters enormously. Cheap capital subsidizes mistakes. Expensive capital exposes them.
If rates remain structurally higher, investors may rediscover a collection of supposedly obsolete concepts: balance sheets, interest coverage, free cash flow, return on invested capital, dilution, debt maturities, liquidation values, accounting quality and, God forbid, valuation.
Mark the Q-man’s words: there are tons of businesses, funds, loans and assets whose health depends on nobody forcing price discovery. There are probably losses buried throughout private markets that have not become losses yet simply because nobody has been required to transact.
And when those losses finally have to be recognized, it could be incredibly ugly. But that is not a bug in capitalism. That is the mechanism. Creative destruction requires destruction. Price discovery requires prices to occasionally discover something unpleasant. Capital allocation requires bad allocators to eventually lose access to capital. Markets cannot distinguish good businesses from bad businesses if everybody gets unlimited time and unlimited financing.
=========================================
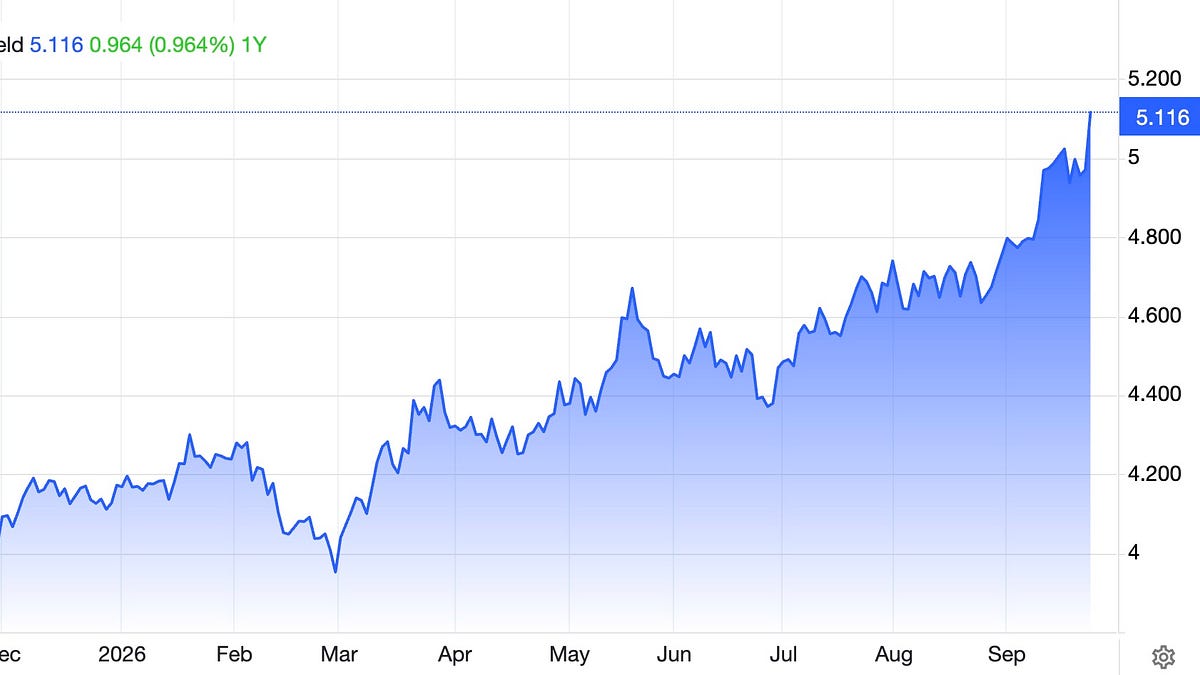
........ It’s as simple as this: as long-term interest rates continue moving higher, virtually every important piece of financial math gets worse, all at the same time.
The discount rate used to value stocks rises, which makes future earnings worth less today. Mortgages get more expensive. Corporate borrowing gets more expensive. Private equity deals and private credit…much of which is already FUBAR but not showing it yet…become harder to finance. Leveraged companies have to refinance debt at higher rates. Consumers pay more to borrow and the federal government pays more to service its enormous pile of debt.
Rising rates are a slow, methodical wood chipper for anything built on cheap money. Anything like…oh, I don’t know…the entire fucking economy of the last two decades—especially after the Fed went full MythBusters during Covid, rejecting the reality of the economy’s death, and substituting its own by papering over the whole thing with $4 trillion in freshly printed cash.
........
That’s what scares me about the setup. We don’t have cheap stocks, low leverage and pristine balance sheets encountering slightly higher rates. We have enormous government debt, enormous consumer debt, enormous corporate borrowing, record margin leverage, stressed private-credit liquidity, speculative AI financing, crypto, gigantic valuations and investors who have been conditioned for nearly two decades to believe that every meaningful decline will eventually be rescued by the Federal Reserve.
Now raise the risk-free rate underneath all of it. And don’t stop doing raising it. Something has to…and will…give. In fact, if bond yields keep climbing, my view is that eventually a lot of things give at the same time.
This could become wrath-of-God-type stuff. Not because I’m predicting the apocalypse, but because there is an extraordinary amount of leverage sitting on top of asset prices that were built for a world where money was cheap, and the bond market is threatening to make money expensive again.
There is, of course, one enormous caveat: bonds can recover. If inflation falls, economic growth slows and long-term yields retreat substantially, the pressure valve opens. Discount rates fall, refinancing fears ease and equity multiples become easier to defend. The whole process can be postponed again.
But if long rates continue grinding higher and the market starts believing 5%-plus Treasury yields aren’t an aberration but the new regime, I don’t see how the current structure survives.
It’ll be a massive wreck. Maybe a crash the likes of which we haven’t seen before. And then my guess remains that the ultimate destination is some form of yield-curve control or similarly aggressive intervention. If policymakers eventually cap Treasury yields while inflation and fiscal deficits remain problematic, I think gold could go absolutely berserk. My long-term $10,000 gold thesis would become considerably less ridiculous.
But people keep skipping over the important part: you don’t get the rescue until something requires rescuing. That means pain first. Potentially enormous pain.
My thesis has become remarkably simple. If the bond market calms down, we can have another conversation. If yields keep going higher from here, I think a massive stock-market crash becomes increasingly difficult to avoid.
Not because of doomsday saying or permabear “fearmongering”, or because Peter Schiff has been yelling about it for 20 years. Because eventually, no matter how much bullshit Wall Street invents, math still eventually wins.
.
Everything Is Fine, Except For Everything
Market breadth is deteriorating at a historic pace as yields surge, flashing huge warning signals under indexes powered by just a handful of stocks.
Everything Is Fine, Except For Everything
Market breadth is deteriorating at a historic pace as yields surge, flashing huge warning signals under indexes powered by just a handful of stocks.
quoththeraven.substack.com
............ In other words, the global cost of capital is repricing higher at exactly the same moment that the internals of the U.S. equity market are deteriorating, and as…in my opinion only…the wheels of the AI trade are starting to fall off in a big way.
The S&P 500 is increasingly behaving like a mansion whose foundation is starting to crack while everybody stands on the roof admiring the view. The capitalization-weighted index remains elevated because a handful of gigantic companies, particularly those associated with the AI trade, carry enough weight to offset weakness almost everywhere else.
But equal-weight stocks are falling. Banks are falling. Midcaps and small caps have been hit harder. Fewer stocks are holding their moving averages. The median stock is nowhere near its high. And those are precisely the areas, along with unprofitable small cap shitcos that need constant capital to survive, where you would expect higher financing costs to begin showing themselves first.
===========================================
It’s Official: The AI Emperor Has No Clothes
Now who is going to be the first to stand up and say it?
It’s Official: The AI Emperor Has No Clothes
Now who is going to be the first to stand up and say it?
quoththeraven.substack.com
Put all of this together and the picture starts becoming difficult to dismiss as a collection of unrelated curiosities.
- Anthropic finally opens its books and reveals astonishing revenue growth sitting alongside staggering losses, enormous compute spending and more than half a trillion dollars of future infrastructure obligations.
- SpaceX goes public at a roughly $1.8 trillion valuation despite having lost almost $5 billion the previous year and another $4.3 billion during the first quarter of 2026.
- Oracle issues a force majeure notice on one of the flagship infrastructure projects underpinning the AI buildout just as its CDS spreads blow out.
- Hyperscaler CDS activity explodes, CCC junk yields push above 16%, Treasury yields surge, and underneath an index still flirting with its highs, market breadth looks awful.
..........The question under this AI bubble is what price investors were willing to pay for the future before that future actually arrives, and whether the economics eventually produced by the technology could justify the enormous amount of capital committed to it along the way.
For the first time during this cycle, we’re beginning to get enough information to actually run those numbers and the credit markets and bond markets are puking them back up at record speed. The cost of capital is rising while the financial statements behind some of the most celebrated companies in the world are finally being laid bare, forcing investors to confront the possibility that enormous technological importance and enormous economic profitability may not necessarily arrive on the same timetable.
Underneath all of the breathless talk about trillion dollar addressable markets and civilization changing productivity, the uncomfortable possibility is that there may not be nearly as much “there” there economically as current valuations have already priced in…at least for this credit cycle.
Investors can now see the financial statements, the credit spreads, the bond yields, the deterioration in market breadth and the extraordinary capital requirements necessary to keep the AI machine running for themselves. The information isn’t hidden anymore. What remains unclear is who will be the first person willing to look at all of it together and simply proclaim that the AI emperor has no clothes…and what happens when everybody else realizes they were just sitting around waiting for someone else to say it first.
==============================================
The Easy Money Fairy Tale Is About To End Violently
The Easy Money Fairy Tale Is About To End Violently
Truth, consequences and pain are on their way. And to the best of what I can tell, no one is prepared psychologically.
quoththeraven.substack.com
............The reason is simple. Higher rates restore consequences. When investors can earn meaningful returns in Treasury securities and other relatively safe assets, they no longer need to finance every revolutionary dog walking blockchain SaaS platform that comes along. Junk bonds have to offer genuinely attractive yields. Private credit has to compete against liquid alternatives. Venture investments have to offer enough potential return to compensate for years of illiquidity and enormous failure rates.
Suddenly, the hurdle rate exists again.
Companies burning cash discover that capital has a price. Companies dependent on refinancing discover that lenders have alternatives. Private equity firms discover that an acquisition financed with cheap debt looks considerably less brilliant when that debt has to be refinanced at twice the rate. Commercial real estate owners discover that capitalization rates matter. Governments discover that deficits carry interest expense. Investors discover that earnings expected fifteen years from now are worth substantially less when the discount rate is no longer zero.
Fraud becomes harder…because fraud loves liquidity. It needs it for sustenance. Liquidity buys time, and a questionable business can survive as long as somebody keeps funding it. Once capital becomes scarce, the runway shortens and the questions become considerably less philosophical. Where is the cash? Who owes whom? What is the collateral actually worth? Can you refinance this? Why does EBITDA never turn into free cash flow? Why are you issuing stock every quarter? Why does every supposedly temporary adjustment show up again next year?
Why, exactly, does this multi-billion dollar company make no fucking money?
........... Higher rates will not make markets perfectly rational either. Markets have been doing stupid things for hundreds of years and will presumably continue doing stupid things long after all of us are dead. But the environment in which stupidity operates matters enormously. Cheap capital subsidizes mistakes. Expensive capital exposes them.
If rates remain structurally higher, investors may rediscover a collection of supposedly obsolete concepts: balance sheets, interest coverage, free cash flow, return on invested capital, dilution, debt maturities, liquidation values, accounting quality and, God forbid, valuation.
Mark the Q-man’s words: there are tons of businesses, funds, loans and assets whose health depends on nobody forcing price discovery. There are probably losses buried throughout private markets that have not become losses yet simply because nobody has been required to transact.
And when those losses finally have to be recognized, it could be incredibly ugly. But that is not a bug in capitalism. That is the mechanism. Creative destruction requires destruction. Price discovery requires prices to occasionally discover something unpleasant. Capital allocation requires bad allocators to eventually lose access to capital. Markets cannot distinguish good businesses from bad businesses if everybody gets unlimited time and unlimited financing.
=========================================
Bonds Are About To Crash The Stock Market
........ It’s as simple as this: as long-term interest rates continue moving higher, virtually every important piece of financial math gets worse, all at the same time.
The discount rate used to value stocks rises, which makes future earnings worth less today. Mortgages get more expensive. Corporate borrowing gets more expensive. Private equity deals and private credit…much of which is already FUBAR but not showing it yet…become harder to finance. Leveraged companies have to refinance debt at higher rates. Consumers pay more to borrow and the federal government pays more to service its enormous pile of debt.
Rising rates are a slow, methodical wood chipper for anything built on cheap money. Anything like…oh, I don’t know…the entire fucking economy of the last two decades—especially after the Fed went full MythBusters during Covid, rejecting the reality of the economy’s death, and substituting its own by papering over the whole thing with $4 trillion in freshly printed cash.
........
That’s what scares me about the setup. We don’t have cheap stocks, low leverage and pristine balance sheets encountering slightly higher rates. We have enormous government debt, enormous consumer debt, enormous corporate borrowing, record margin leverage, stressed private-credit liquidity, speculative AI financing, crypto, gigantic valuations and investors who have been conditioned for nearly two decades to believe that every meaningful decline will eventually be rescued by the Federal Reserve.
Now raise the risk-free rate underneath all of it. And don’t stop doing raising it. Something has to…and will…give. In fact, if bond yields keep climbing, my view is that eventually a lot of things give at the same time.
This could become wrath-of-God-type stuff. Not because I’m predicting the apocalypse, but because there is an extraordinary amount of leverage sitting on top of asset prices that were built for a world where money was cheap, and the bond market is threatening to make money expensive again.
There is, of course, one enormous caveat: bonds can recover. If inflation falls, economic growth slows and long-term yields retreat substantially, the pressure valve opens. Discount rates fall, refinancing fears ease and equity multiples become easier to defend. The whole process can be postponed again.
But if long rates continue grinding higher and the market starts believing 5%-plus Treasury yields aren’t an aberration but the new regime, I don’t see how the current structure survives.
It’ll be a massive wreck. Maybe a crash the likes of which we haven’t seen before. And then my guess remains that the ultimate destination is some form of yield-curve control or similarly aggressive intervention. If policymakers eventually cap Treasury yields while inflation and fiscal deficits remain problematic, I think gold could go absolutely berserk. My long-term $10,000 gold thesis would become considerably less ridiculous.
But people keep skipping over the important part: you don’t get the rescue until something requires rescuing. That means pain first. Potentially enormous pain.
My thesis has become remarkably simple. If the bond market calms down, we can have another conversation. If yields keep going higher from here, I think a massive stock-market crash becomes increasingly difficult to avoid.
Not because of doomsday saying or permabear “fearmongering”, or because Peter Schiff has been yelling about it for 20 years. Because eventually, no matter how much bullshit Wall Street invents, math still eventually wins.
.
Chokolinho
Known around here
Peter Schiff.
He IS a gold bug for sure.

But like a broken clock, one of these days he’s gonna be right again

